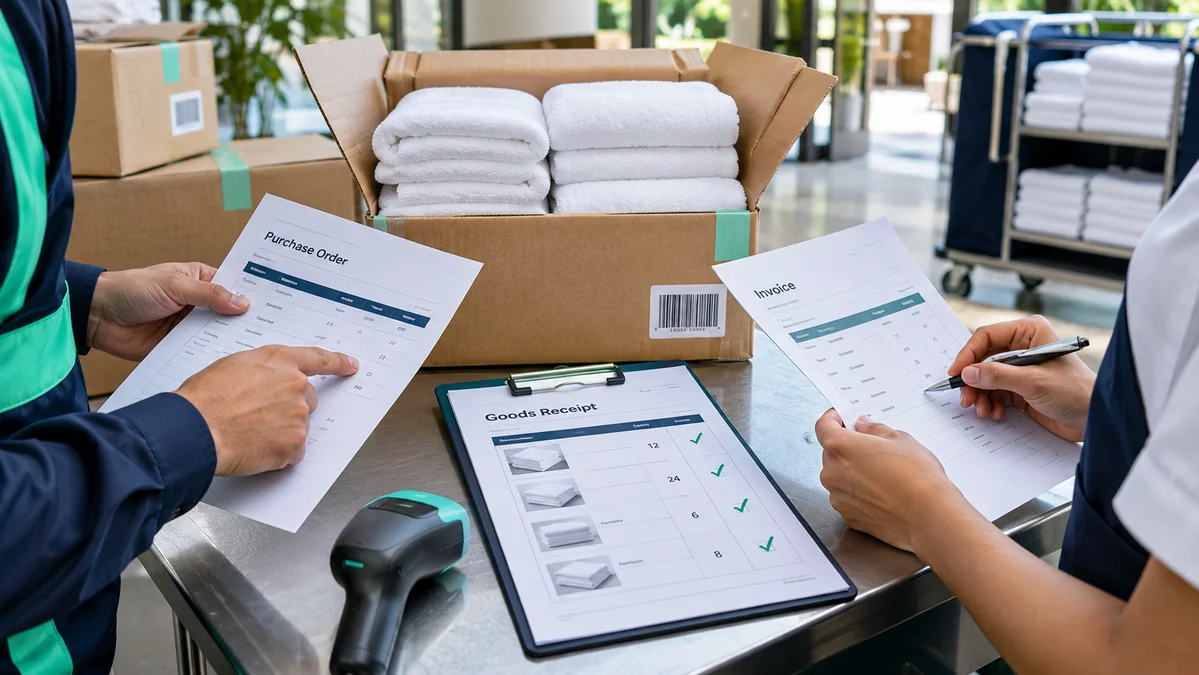
The store has received the goods, but the supplier invoice has not arrived. Elsewhere, AP has recorded an invoice while the receipt is still missing. These are the kinds of differences that collect in the goods receipt/invoice receipt clearing account, usually called GR/IR.
At month-end, the useful question is what each open purchase-order item represents and what evidence will clear it. An old balance can be a missing invoice, an incomplete receipt, a price difference or a posting error. Age alone does not tell you which action to take.
Understand the normal accounting flow
For a simple inventory purchase with no tax or price difference, receipt of goods debits inventory and credits GR/IR. Posting the matching invoice debits GR/IR and credits the vendor. Both postings refer to the same purchase-order item. For an expense purchase, the debit at receipt may be an expense account, depending on the purchasing and accounting setup.
| Event | Debit | Credit |
|---|---|---|
| Receive goods valued at ₹1,00,000 | Inventory ₹1,00,000 | GR/IR ₹1,00,000 |
| Record matching supplier invoice | GR/IR ₹1,00,000 | Vendor payable ₹1,00,000 |
The matched value offsets in GR/IR. The software’s clearing status and open-item processing depend on configuration. Tax, delivery costs and price variances can use other accounts, so trace the actual accounting documents when a balance does not match the simple model.
Work through a partial invoice
A hotel orders 100 units of linen at ₹1,000 each. Stores receives all 100 units before month-end, creating a ₹1,00,000 credit in GR/IR. AP receives an invoice for only 80 units at the same price and debits GR/IR by ₹80,000. The remaining ₹20,000 credit represents 20 received units awaiting an invoice in this example.
Ask whether the supplier will bill the remaining units, whether the invoice quantity is wrong or whether stores recorded an incorrect receipt. Keep the PO, receipt and invoice references together. If a later invoice arrives for the remaining 20 units at the same price, it offsets the outstanding value. The example excludes taxes and other price adjustments.
Review debit and credit positions separately
| Position in the simple model | Likely question | Evidence to inspect |
|---|---|---|
| Credit balance | Were goods received without a matching invoice? | GRN, PO history, supplier statement and invoice register |
| Debit balance | Was an invoice posted before the corresponding receipt? | Invoice, delivery evidence and receipt status |
| Quantity mismatch | Is a partial delivery or partial invoice still expected? | PO item quantities and returns |
| Price or delivery-cost difference | Was the agreed price or allocation followed? | PO amendments, invoice and accounting documents |
Build the review at purchase-order item level. Offsetting a credit on one order with a debit on another can hide two unresolved problems. Group by entity, currency, supplier and PO item, and retain the full original posting history for investigation.
A practical month-end review sequence
- Tie the GR/IR report to the general ledger at the same cutoff.
- Separate received-not-invoiced items from invoiced-not-received items.
- Identify partial quantities, returns, reversals and duplicate postings.
- Age items from the relevant open transaction and document the policy used.
- Ask purchasing, stores and AP for evidence and expected completion dates.
- Record each approved correction and rerun the reconciliation.
- Review the financial-statement presentation required by the applicable framework.
Avoid creating a second liability
If receipt accounting has already recognised inventory or an expense with a credit in GR/IR, a separate expense accrual for the same goods can duplicate the liability. Reconcile the receipt account before adding an unbilled expense schedule. For services, inspect the service confirmation and the posting policy rather than assuming the goods example applies unchanged.
Clear or write off an item only when the facts support it and the required approval exists. A final invoice indicator or an old PO does not replace evidence that further deliveries or invoices are no longer expected. SAP’s documented clearing process includes checks and correction options, but availability and transaction behaviour vary by product and configuration. Retain the explanation, documents and approval with the close file.
- SAP GR/IR clearing account definition
- SAP Clear GR/IR Clearing Account
- Vendor reconciliation
- Accrued and prepaid expenses
Prepared by the TaxNexus Editorial Team. Last reviewed 6 November 2026. All amounts and business records in the worked examples are illustrative. Apply your organisation’s accounting policies and review the applicable tax treatment before posting entries.