TDS & Payroll Compliance in India
Understand deduction, deposit, quarterly reporting, Form 16/16A, salary-TDS controls, payroll reconciliation and year-end checks for FY 2026-27.
Editorial standards: About TaxNexus · Editorial Policy · Disclaimer
Tax Deducted at Source is a collection mechanism: the deductor withholds tax from specified payments and deposits it with the Government, while the deductee claims credit in the income-tax return. In payroll, TDS works alongside salary structure, exemptions, deductions, provident fund and other statutory items, so a reliable month-end process should reconcile gross pay, taxable pay, tax deducted, challan payment, quarterly return and employee tax credit.
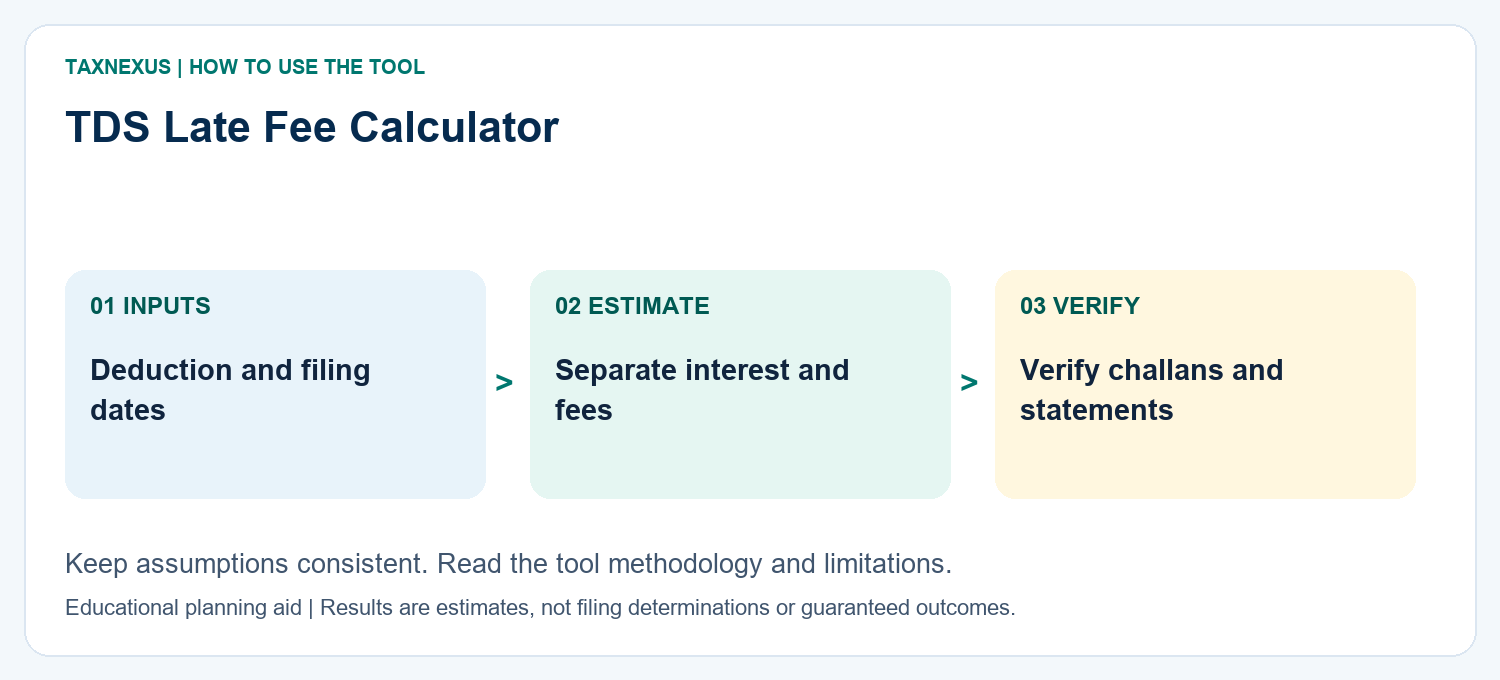
TDS Late Fee & Interest Calculator
Payroll Reconciliation Guide
Income Tax in India Guide
1. Current 2026-27 TDS framework
The Income Tax Department’s current guidance states that the newer income-tax law consolidates TDS provisions in a tabular structure under section 393 for payments from 1 April 2026, while the underlying TDS rates and monetary thresholds were retained at transition. The Department also cautions that using an old section reference for a post-1-April-2026 transaction can create return-processing issues even where the rate itself is correct.
2. When TDS applies
TDS can apply to salary and many non-salary payments such as interest, contractor payments, professional or technical fees, rent, commission and other specified categories. The trigger can depend on payment type, threshold, recipient status and whether tax is required at credit or payment, whichever is earlier.
For salary, the employer estimates annual taxable salary, considers the employee’s eligible declarations/proofs and applicable tax regime, and spreads the expected tax deduction over the remaining payroll periods.
3. Salary TDS and payroll calculation flow
- Establish annual salary components and taxable perquisites.
- Identify exemptions/deductions permitted under the employee’s applicable tax regime.
- Include other income declared by the employee where the law permits the employer to consider it.
- Estimate annual taxable income and tax liability.
- Reduce eligible tax already deducted and allocate the balance across remaining salary months.
- Recompute when salary changes, bonus is paid, declarations change or an employee joins/leaves during the year.
For current slab information and regime comparison, use the Income Tax in India guide and Old vs New Tax Regime Calculator.
4. Payroll reconciliation: monthly control
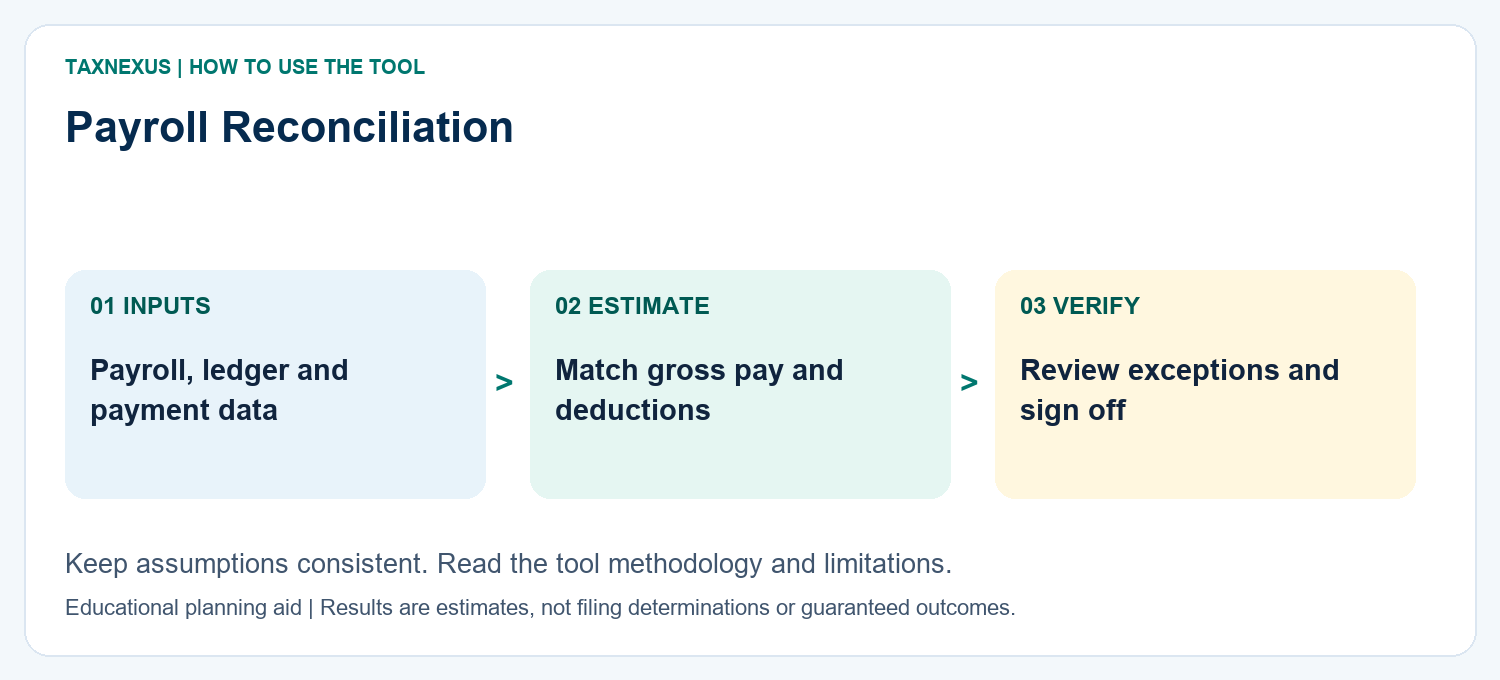
A payroll reconciliation should tie the HR/payroll register to accounting and statutory records. At minimum, reconcile:
- Employee count, attendance and paid days.
- Basic, DA, HRA, allowances, incentives, bonus and other earnings.
- Employee PF, professional tax, TDS and other deductions.
- Employer PF and other employer-cost components.
- Net salary payable to the bank payment file.
- Payroll expense and liability ledgers in the general ledger.
- TDS deducted to challan payment and quarterly TDS statement.
- PF contribution to the applicable EPFO filing/payment records.
See the detailed Payroll Reconciliation: Process, Checklist & Journal Entries guide for a month-end workflow.
5. EPF in payroll
EPFO’s published contribution guidance shows the standard employee contribution at 12% for covered establishments, with specific cases where a 10% rate may apply. Employer contribution is allocated between EPF/EPS and related components under the applicable rules. Wage ceilings and higher-wage contribution choices can affect the actual calculation.
Use the EPF Calculator for planning, but verify the establishment’s applicable contribution basis and EPFO rules before payroll finalisation.
6. TDS deposit, return and certificate control
After deduction, the compliance chain does not end with the payroll run. Finance should track the amount through deposit, return filing and employee/vendor credit. A strong control file contains the deduction working, challan identification, quarterly return acknowledgement and the corresponding certificate.
| Control | What to match |
|---|---|
| Books vs deduction working | Taxable base, category, rate and TDS amount |
| Deduction vs challan | Amount, period and deductor details |
| Challan vs quarterly return | Correct challan tagging and deductee allocation |
| Return vs Form 16/16A | Employee/vendor tax certificate values |
| Return vs tax credit | Credit reflected for the deductee |
7. Practical TDS reconciliation example
Assume an invoice has a taxable base of ₹1,00,000 and the verified applicable rate for that transaction is 2%. Expected TDS is ₹2,000. If the ledger, challan and quarterly return each show ₹2,000, the item is matched.
If the deduction working shows ₹7,500 but only ₹7,000 was actually deducted, investigate the ₹500 difference before filing. Typical checks include the current section mapping, threshold, PAN status, taxable base, adjustments and whether part of the deduction was posted separately.
8. TDS reconciliation Excel template
Use the TaxNexus reconciliation template to compare books, deduction working, challans and return reporting, including old and new section-reference fields.
Download TDS Reconciliation Excel Template
9. Year-end payroll and Form 16 checklist
- Reconcile annual payroll earnings to the general ledger.
- Review joiners, leavers, arrears, bonus and one-time payments.
- Confirm employee tax-regime and declaration/proof treatment.
- Reconcile monthly TDS deductions to challans and quarterly statements.
- Review PAN and employee master data.
- Check final taxable salary and tax deduction before year-end payroll closure.
- Generate and validate Form 16 after the required filing/processing steps.
10. Common TDS and payroll errors
- Using an outdated section reference after a law transition.
- Applying a rate without checking the threshold or recipient status.
- Deducting correctly but depositing or reporting under the wrong challan/period.
- Not recomputing salary TDS after a bonus or salary revision.
- Payroll register not matching the bank file or general ledger.
- TDS return values not matching Form 16/16A or employee/vendor tax credit.
11. Official references
Verify current TDS requirements on the Income Tax Department TDS Compliance guidance. For provident-fund contribution rules and employer/member services, use the Employees’ Provident Fund Organisation.